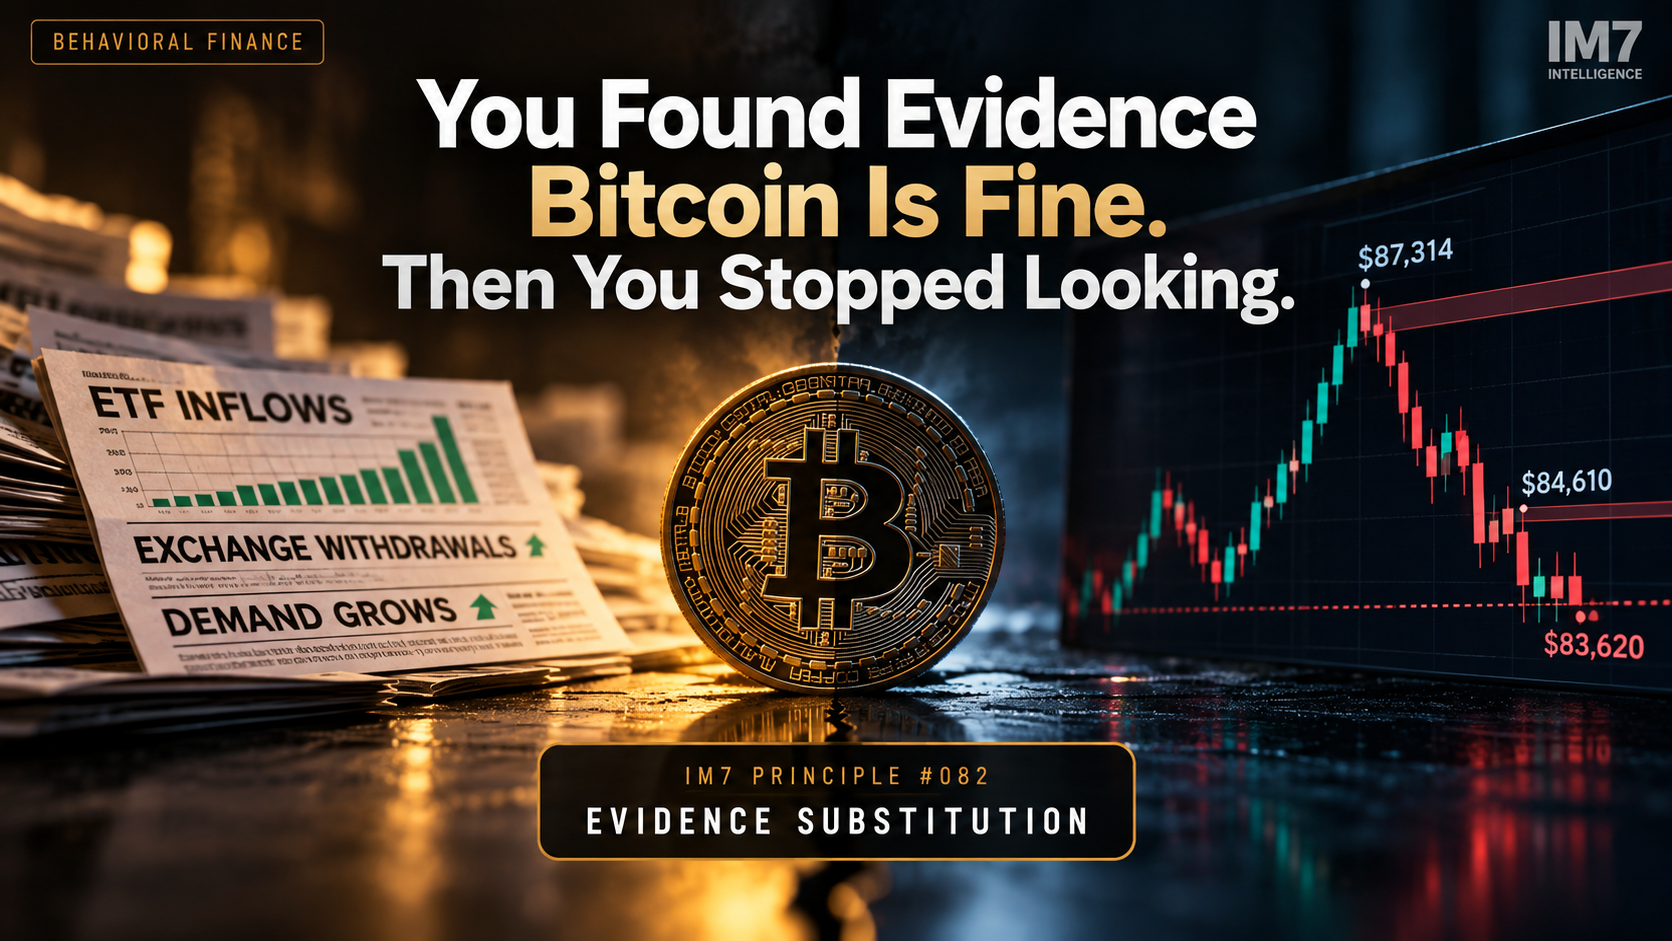
You Found Evidence Bitcoin Is Fine. Then You Stopped Looking.
AI Generated • IM7 Intelligence
- Reading time
- 5 min read
- Word count
- 1,074 words
- Published
Bitcoin traders have real evidence supporting both sides of the current debate. The behavioral mistake begins when supporting evidence becomes a reason to stop looking. Evidence Substitution explains why evidence that agrees with your position is not the same as evidence that the market has confirmed it.
Executive Summary
Bitcoin is presenting traders with something psychologically difficult: credible evidence on both sides of the argument.
U.S. spot Bitcoin ETFs recorded roughly $190.7 million of net inflows on September 24, extending a six-session positive streak, even as Bitcoin retreated from above $87K and the latest 2-hour chart showed price back near $83.6K. :contentReference[oaicite:0]{index=0}
The behavioral mistake is not believing the bullish evidence or the bearish evidence. It is finding evidence that supports an existing belief and allowing that evidence to end the investigation.
That is Evidence Substitution: evidence for your position becomes a substitute for evidence that the market has actually confirmed it.
IM7 Principle
IM7 Principle #082 — Evidence Substitution
When traders already hold a market belief, evidence supporting that belief can become a substitute for evidence that the market has actually confirmed it.
The problem is not finding valid evidence.
The problem is allowing agreeable evidence to end the search.
Market Context
Bitcoin's current setup contains legitimate evidence that can support competing interpretations.
On the demand side, U.S. spot Bitcoin ETFs recorded approximately $999.0M, $714.7M, $346.9M and $190.7M of net inflows from September 21 through September 24. The flows remained positive, although their daily magnitude declined across those four sessions. :contentReference[oaicite:1]{index=1}
Price has been less decisive.
Bitcoin pushed above $87K earlier in the week before retreating. By September 25, the market had returned toward the $84K region, while the supplied 2-hour chart subsequently showed BTC around $83,620 after another attempt toward roughly $84.6K failed to hold. Independent market reporting also recorded a September 25 trading range extending below $83K. :contentReference[oaicite:2]{index=2}
Those observations do not require one another to be false.
ETF demand can be real while price confirmation remains incomplete.
That distinction creates today's behavioral setup.
What The Market Wanted You To Believe
"I found the evidence. My side is confirmed."
A bullish trader can point to persistent ETF inflows.
A cautious or bearish trader can point to Bitcoin's retreat after trading above $87K.
Both observations contain information.
But neither observation, isolated from everything else, gives the trader permission to stop evaluating the market.
That is where evidence becomes psychologically dangerous.
The trader stops asking:
"What is the market showing me?"
And begins asking:
"What proves I was right?"
The evidence may still be accurate.
The interpretation becomes incomplete.
Behavioral Observation
Watch what happens after a trader develops a directional belief.
New information stops receiving equal scrutiny.
Evidence that agrees with the existing position gets collected:
"See? I knew it."
Evidence that complicates the position gets explained away:
"That's just noise."
The behavioral signal is not confidence itself.
It is the moment the trader's standard of evidence changes depending on whether the information agrees with the conclusion already reached.
Cognitive Bias Breakdown
The established psychological mechanism underneath this behavior is [confirmation bias](/library/confirmation-bias).
Research on biased assimilation shows that people can evaluate evidence differently depending on whether it supports or challenges an existing belief [Lord, Ross & Lepper, 1979].
Evidence Substitution is the IM7 market application of that broader mechanism.
The trader does not necessarily invent evidence.
That distinction matters.
ETF inflows can be real.
A rejection can be real.
Exchange withdrawals can be real.
A defended price level can be real.
The behavioral error occurs when one valid piece of information is promoted into something it does not establish:
market confirmation.
Supporting evidence answers:
"Is there evidence for my thesis?"
Confirmation requires another question:
"Is the market behaving in a way that validates the conclusion I am drawing from that evidence?"
Those are not the same test.
The Professional Read
A disciplined operator does not need every piece of evidence to point in the same direction.
Conflicting evidence is information too.
The professional read separates evidence into categories rather than forcing everything into a single conclusion.
Demand evidence: Are buyers or capital flows present?
Price evidence: Is price accepting or rejecting important areas?
Behavioral evidence: How is the market responding when new information arrives?
Confirmation evidence: Has the condition required by the thesis actually occurred?
This prevents a strong data point in one category from automatically answering a different question.
ETF inflows can demonstrate demand without independently proving that every pullback has ended.
A rejection can demonstrate resistance without independently proving that the broader recovery has failed.
The disciplined response is not:
"Which evidence do I like?"
It is:
"What does each piece of evidence actually prove?"
Decision Framework
Before using new evidence to reinforce a market belief, ask:
- What exactly does this evidence establish?
- What does it not establish?
- Would I give this evidence the same weight if it contradicted my position?
- What evidence on the other side am I currently discounting?
- Has price actually confirmed the conclusion I am drawing?
- Am I updating my thesis, or defending one I already formed?
- What observable condition would force me to reconsider?
If you cannot answer the final question, you may no longer be testing a thesis.
You may be protecting one.
Risk Management Lesson
Evidence Substitution becomes more dangerous when position size creates a psychological need to be right.
The more a trader needs a particular outcome, the more valuable agreeable evidence becomes emotionally.
That can turn research into reassurance.
Position sizing therefore protects more than capital.
It protects the trader's ability to remain curious when the market produces uncomfortable information.
If uncertainty is financially tolerable, contradictory evidence becomes easier to examine instead of dismiss.
IM7 Quote
"Evidence for your position isn't evidence the market agreed with you."
IM7 Observation
The dangerous trader is not always the trader with bad information.
Sometimes it is the trader with good information used for the wrong conclusion.
That distinction matters in the current Bitcoin market.
There is evidence of demand.
There is evidence of rejection.
There is evidence that buyers remain active.
There is also evidence that price has not simply accepted every level reached during the rebound.
The market does not owe those observations an immediate resolution.
The trader's job is not to select the evidence that feels most comfortable.
It is to continue reading until behavior provides stronger confirmation.
Touch isn't hold.
Hold isn't acceptance.
And evidence isn't confirmation.
IM7 Decision Rule
Before calling supporting evidence confirmation, identify what the market itself would have to do to validate your conclusion.
If that condition has not occurred, keep the evidence — but keep the question open.
How did this land?
What emotion or bias did this article help you recognize?
References
- [1]Lord, C. G., Ross, L. & Lepper, M. R. (1979). Biased Assimilation and Attitude Polarization: The Effects of Prior Theories on Subsequently Considered Evidence. Journal of Personality and Social Psychology. American Psychological Association. DOI: 10.1037/0022-3514.37.11.2098. https://doi.org/10.1037/0022-3514.37.11.2098 (accessed 2026-09-25)
Pass the signal forward.
IM7 Intelligence studies financial markets through the lens of psychology rather than prediction. Our research focuses on behavioral finance, crowd psychology, sentiment, and decision-making to help readers understand why markets move—not just where they move.
IM7 Intelligence publishes educational research on market psychology, behavioral finance, and investor behavior. Nothing published by IM7 Intelligence constitutes financial, investment, tax, or legal advice. Always conduct your own research before making financial decisions.
Read the market's emotion before it acts.
Where this article sits in the map.
- Confirmation BiasYou are here
- Behavioral Finance
- Risk Management
- Fear
Curated paths, not random articles.
Behavior read in real time.

Ismael Mercius
Ismael Mercius is the founder of IM7 Intelligence, where he writes about crypto market psychology, behavioral finance, and the sentiment cycles that drive digital asset prices. His work focuses on how traders actually make decisions — and the recurring errors that show up in their P&L.
- Crypto market psychology
- Behavioral finance
- Market sentiment analysis
- Trader behavior & decision-making