$2.4B Flowed Into Bitcoin ETFs. So Why Couldn't Bitcoin Hold $85K?
AI Generated • IM7 Intelligence
- Reading time
- 5 min read
- Word count
- 1,143 words
- Published
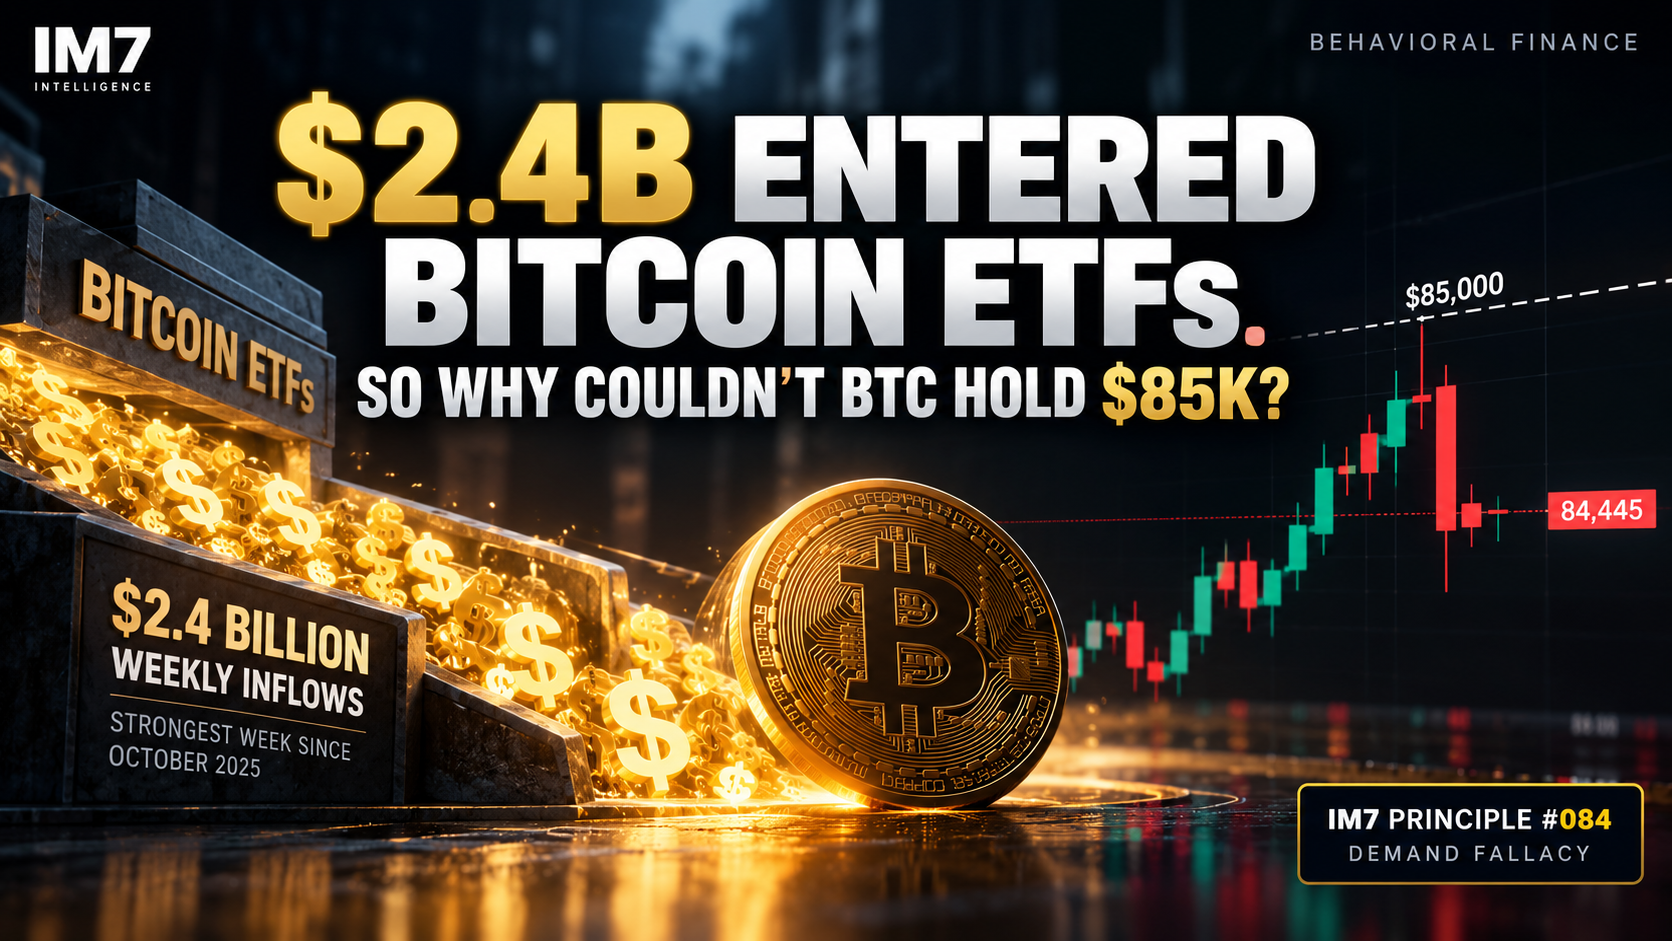
U.S. spot Bitcoin ETFs attracted roughly $2.4 billion in net inflows during the week, yet Bitcoin failed to sustain its move through $85K. Demand Fallacy explains why traders can mistake the size of buying pressure for proof of the market outcome instead of asking whether that demand actually changed price behavior.
Executive Summary
U.S. spot Bitcoin ETFs absorbed roughly $2.4 billion in net inflows during the week ending September 25, their strongest week since October 2025. Yet Bitcoin's latest 2-hour push toward $85K failed to sustain itself, with price returning toward the mid-$84K area.
That creates a behavioral trap: traders see an unusually large demand number and mentally convert it into an expected price outcome. But demand and outcome are not the same variable. Large buying can be real while the market simultaneously reveals enough opposing supply to prevent that demand from producing the move traders expected.
The lesson is not to ignore ETF demand. It is to stop treating the size of an input as proof of the market's response.
IM7 Principle
IM7 Principle #084 — Demand Fallacy
Demand Fallacy occurs when traders treat the magnitude of buying pressure as proof that price must produce a particular outcome.
Strong demand tells you that buyers are participating. It does not tell you whether that demand is large enough to overwhelm the supply meeting it.
Market Context
U.S. spot Bitcoin ETFs recorded approximately $2.4 billion in net inflows for the week ending September 25, the largest weekly inflow since October 2025.
Monday alone accounted for roughly $999 million, followed by progressively smaller positive daily inflows of approximately $714.7 million, $347 million, $190.6 million and $134.5 million.
Bitcoin had already responded strongly earlier in the week, briefly trading above $87K on Monday before retreating.
By Sunday, the 2-hour chart was presenting a different question.
Price pushed back toward the $85K area, briefly traded above it, and then produced a sharp rejection candle back toward approximately $84.4K.
The ETF demand remained meaningful.
The price response was no longer as simple.
That separation matters.
What The Market Wanted You To Believe
"$2.4 billion came in. Bitcoin has to go higher."
The number makes the conclusion feel almost mathematical.
If billions of dollars are flowing into Bitcoin products, the intuitive reaction is that price should rise.
And sometimes it does.
The mistake begins when the trader stops treating demand as one piece of evidence and starts treating it as the predetermined outcome.
A $2.4 billion inflow week establishes that meaningful demand existed.
It does not establish that every seller has disappeared, that resistance must break, or that price must continue moving higher on the trader's preferred timetable.
The market can absorb substantial buying without producing the price expansion traders expected.
When that happens, the failure of price to respond becomes evidence too.
Behavioral Observation
Watch what happens when traders encounter an unusually large number.
$2.4 billion.
The size creates psychological weight.
The trader stops asking:
"What did price do with that demand?"
And starts saying:
"With that much demand, price has to go higher."
Those sound similar.
They are completely different statements.
One observes the relationship between demand and price.
The other assumes the relationship in advance.
That is the behavioral signal to look for on the chart: strong positive evidence arriving without an equally strong price response.
When the headline becomes more convincing than the tape, the trader may be measuring participation while assuming outcome.
Cognitive Bias Breakdown
The brain prefers easier questions.
Instead of answering the harder question:
"Was this demand sufficient to change the balance between buyers and sellers?"
the trader can unconsciously substitute an easier one:
"Was the demand large?"
This resembles what behavioral researchers describe as attribute substitution: when a difficult judgment is replaced by an easier, more accessible judgment Kahneman & Frederick, 2002.
Here, the substituted variable is demand magnitude.
The original variable is market impact.
That distinction is critical.
Large demand can coexist with:
- large supply,
- profit-taking,
- hedging,
- resistance,
- liquidity concentration,
- or other selling pressure.
You do not need to know exactly who is selling to observe the consequence.
If unusually strong demand arrives and price cannot sustain progress, the response itself contains information.
Demand Fallacy happens when the trader keeps staring at the size of the buying while discounting what price did with it.
The Professional Read
A disciplined operator does not dismiss the ETF flows.
They separate input from response.
The input:
Approximately $2.4 billion of weekly ETF net inflows.
The response:
Bitcoin advanced strongly earlier in the week, but its latest attempt around $85K was not sustained.
Those facts can coexist.
The professional question therefore is not:
"Are ETF inflows bullish?"
It is:
"How much market progress is this demand currently producing?"
That changes the analysis.
If significant demand produces expanding price acceptance, the evidence is behaving one way.
If significant demand produces limited additional progress, repeated rejection, or compression, the evidence is behaving differently.
Neither observation requires a prediction.
It requires measuring the market's response to the information already known.
Decision Framework
When a large demand number enters your thesis, separate it into five questions:
1. What is the input? How much demand actually appeared?
2. What was the price response? Did price expand, stall, reject, or remain unchanged?
3. Was the response proportional? Did unusually strong demand produce unusually strong market progress?
4. What happened after the first reaction? Did the market sustain the move or surrender it?
5. What evidence am I actually trading? The size of the headline — or the market's response to it?
The goal is not to diminish strong demand.
The goal is to measure whether the demand is changing the auction.
Risk Management Lesson
The most dangerous version of Demand Fallacy appears when position size increases because the trader believes the demand number makes the outcome more certain.
Large flows can improve a thesis without eliminating uncertainty.
If price stops responding proportionally to the evidence supporting your position, increasing conviction simply because the underlying number remains impressive can create asymmetric risk.
Risk should respond to what the market is currently confirming — not only to how persuasive the original evidence sounds.
IM7 Quote
"Demand tells you who showed up. Price tells you whether it mattered."
IM7 Observation
Large numbers create authority.
They feel objective, measurable and difficult to argue with.
That is exactly why they can become dangerous.
The problem with $2.4 billion of ETF demand is not that the number is misleading.
The number is real.
The behavioral mistake is asking the number to answer a question it cannot answer by itself.
It can tell you that substantial demand entered the market.
It cannot tell you, without price confirmation, whether that demand has overwhelmed everything sitting on the other side.
Markets are not determined by the existence of buyers.
They are determined by the interaction between buyers and sellers.
IM7 Decision Rule
When unusually strong demand appears, measure what price accomplished with it before increasing confidence.
If the demand is large but the market response is limited, treat that divergence as new evidence rather than assuming the demand must eventually win.
How did this land?
What emotion or bias did this article help you recognize?
References
- [1]Kahneman, D. & Frederick, S. (2002). Representativeness Revisited: Attribute Substitution in Intuitive Judgment. Heuristics and Biases: The Psychology of Intuitive Judgment. Heuristics and Biases: The Psychology of Intuitive Judgment. DOI: 10.1017/CBO9780511808098.004. https://www.cambridge.org/core/books/abs/heuristics-and-biases/representativeness-revisited-attribute-substitution-in-intuitive-judgment/AAB5D933A3F944CFB5CB02265D376C8F (accessed 2026-09-27)
Pass the signal forward.
IM7 Intelligence studies financial markets through the lens of psychology rather than prediction. Our research focuses on behavioral finance, crowd psychology, sentiment, and decision-making to help readers understand why markets move—not just where they move.
IM7 Intelligence publishes educational research on market psychology, behavioral finance, and investor behavior. Nothing published by IM7 Intelligence constitutes financial, investment, tax, or legal advice. Always conduct your own research before making financial decisions.
Read the market's emotion before it acts.
Where this article sits in the map.
- Confirmation BiasYou are here
- Behavioral Finance
- Risk Management
- Fear
Curated paths, not random articles.
Behavior read in real time.

Ismael Mercius
Ismael Mercius is the founder of IM7 Intelligence, where he writes about crypto market psychology, behavioral finance, and the sentiment cycles that drive digital asset prices. His work focuses on how traders actually make decisions — and the recurring errors that show up in their P&L.
- Crypto market psychology
- Behavioral finance
- Market sentiment analysis
- Trader behavior & decision-making